How to Check if a Contractor Has Insurance (And Why a License Alone Is Not Enough)
Learn how to check contractor insurance before work begins. Free methods, what to verify, and why a license alone leaves you exposed to real financial risk.
You need to check contractor insurance before you sign anything, hand over a deposit, or let a crew step onto your property. A license proves the contractor passed a test at some point. Insurance is what stands between you and a five-figure lawsuit if a worker falls off your roof or a burst pipe floods the house next door.
Most homeowners assume a licensed contractor is automatically insured. That assumption has cost people their savings. Licenses and insurance are two separate things, issued by two separate systems, and one does not guarantee the other. Here is exactly how to verify both before work begins.
What Is the Difference Between a Licensed and an Insured Contractor?
A license is a state or municipal credential that says the contractor met minimum requirements to operate in a trade: passing an exam, meeting experience thresholds, sometimes posting a bond. It is a competency signal. It does not cover damages if something goes wrong on your job.
Insurance is a separate contract between the contractor and an insurance carrier. It pays out when a worker gets hurt, when the contractor damages your property, or when a mistake causes harm to a third party. A contractor can be fully licensed and carry zero active insurance. When that combination shows up on your job site and something breaks, your homeowners policy becomes the payer of last resort.
The gap is bigger than most people realize. According to the Insurance Information Institute, if an uninsured contractor damages your property or injures a worker, you can be held financially responsible. That is why every credible verification standard treats license and insurance as two independent checks, not one.
What Types of Insurance Should a Contractor Carry?
There are three coverages you should expect any legitimate contractor to hold. Each protects you from a different failure mode.
General Liability Insurance
This covers damage the contractor causes to your property or to a third party. If a crew drops a ladder through your bay window or a paint sprayer overshoots onto your neighbor’s car, general liability pays the claim. Minimum coverage for most residential trades runs $1 million per occurrence, though some larger jobs warrant $2 million.
Workers Compensation Insurance
This covers medical bills and lost wages when a worker gets injured on your property. Without it, an injured worker can sue you as the property owner. Workers comp requirements vary by state, but if the contractor has employees, this coverage is almost always mandatory.
Commercial Auto Insurance
If the contractor drives to your job, commercial auto covers accidents involving work vehicles. Personal auto policies typically exclude business use, so a contractor relying on a personal policy leaves a coverage gap.
How Do I Check if a Contractor Has Insurance Online?
You have three practical routes, and you should use more than one when the stakes are high.
Ask for a Certificate of Insurance
A certificate of insurance, called a COI, is a one-page document issued by the contractor’s insurance carrier that summarizes active coverages, policy numbers, limits, and expiration dates. Any legitimate contractor can produce a current COI within a business day. If they stall, hedge, or send one dated a year ago, treat that as a red flag.
Ask for the COI to be sent directly from the insurance carrier or agent, not forwarded by the contractor. Forged COIs are common enough that reputable verification platforms scan every document against carrier records rather than trusting the PDF at face value.
Call the Insurance Carrier Directly
Once you have the COI, call the phone number of the insurance carrier listed on it, not any number the contractor provides. Ask the carrier to confirm the policy is active, the coverage limits match the COI, and the policy has not been canceled. This is the single most reliable free check available to any homeowner.
Check the State License Board
Most state contractor license boards publish an online lookup where you can search a contractor by name or license number. These lookups often display whether the contractor has a workers compensation policy on file and sometimes list the carrier. State board databases are a good cross-reference, but they are not always updated the moment a policy lapses, so pair the lookup with a direct carrier call.
Can I Find a Contractor’s Insurance Information for Free?
Yes. Every method above is free. State license board lookups are free. Calling an insurance carrier to verify a policy is free. Requesting a COI from a contractor is free. The only cost is your time, and on a job worth thousands of dollars, thirty minutes of verification is the highest-return work you will do that week.
Third-party verification services also exist that check contractor insurance against issuing sources on your behalf. Platforms like TradeCheck USA confirm license and insurance against the state board and the insurance carrier directly, and re-check on a set cadence so an expired policy does not sit in a database for months looking active. That is how a verified badge stays honest instead of becoming decorative.
What to Watch Out For When You Check Contractor Insurance
Even when a contractor produces documents, a few patterns should slow you down:
- A COI dated more than 90 days ago. Policies get canceled for nonpayment more often than most homeowners realize.
- Coverage limits below $500,000 general liability. That is thin for anything beyond a minor cosmetic job.
- A COI that names a business entity different from the one on the contract. Sometimes contractors carry insurance on one entity and bill through another. If the names do not match, coverage may not apply to your job.
- Reluctance to name you as an additional insured on the policy for the duration of the project. This is a standard, no-cost request for larger jobs and protects you directly if something goes wrong.
- A workers comp exemption certificate offered in place of a real policy. Exemptions are legitimate for sole proprietors, but if a crew of four shows up, the exemption does not cover them.
Why Verification Cannot Be Self-Reported
A contractor can print a badge on a website. A contractor can list a license number on a truck. Neither confirms the credential is current. This is the core problem with review platforms and marketplace badges: most of them accept whatever the contractor submits and display it without checking the source.
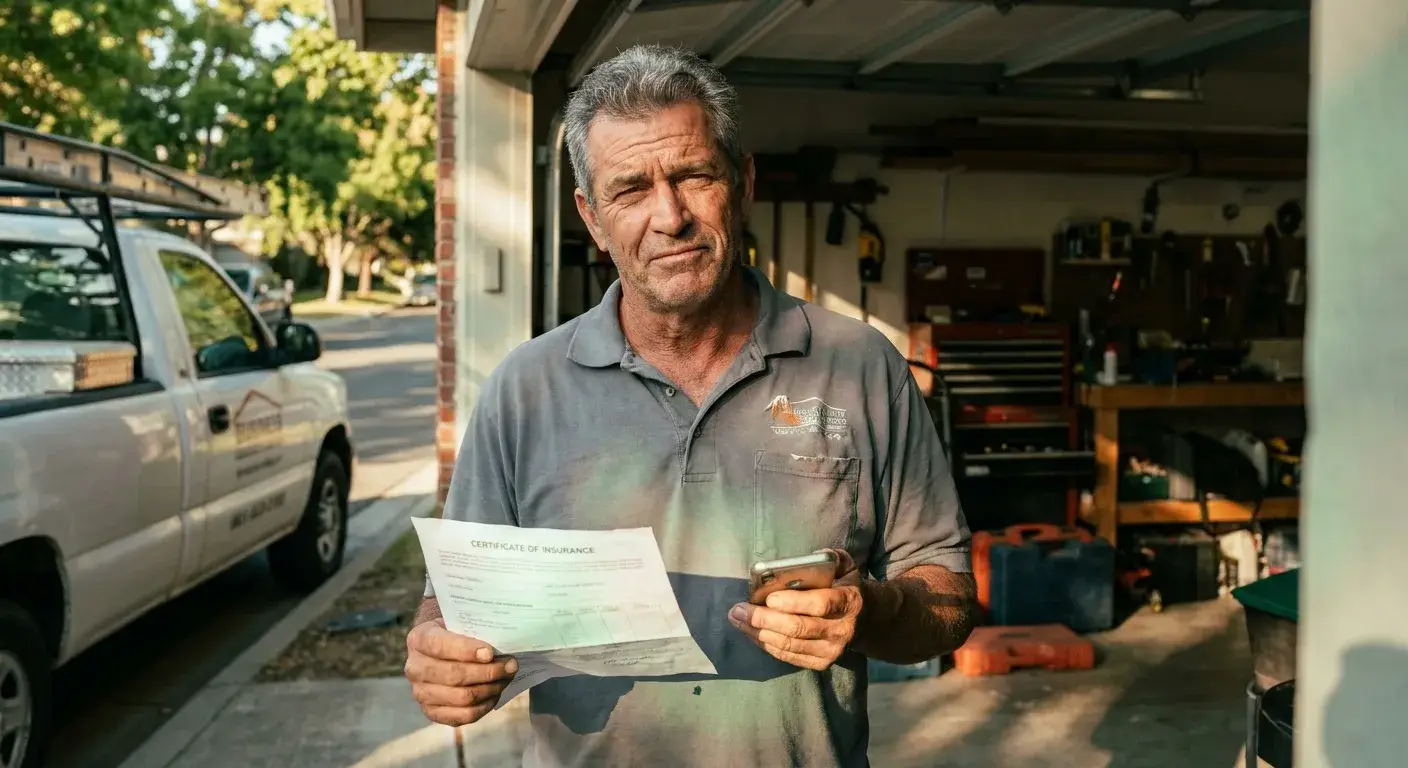
Independent verification means the check runs against the issuing authority, the state license board for the license, the insurance carrier for the policy, and repeats on a cadence so the badge lapses when the coverage lapses. That is the difference between a claim and a confirmed fact, and it is why verification-first platforms treat placement as something earned by passing checks rather than something sold to the highest bidder.
Before You Sign the Contract
Run this short checklist on any contractor before you commit:
- Get the license number and verify it on the state board site.
- Request a current COI, dated within 30 days.
- Call the insurance carrier directly using the number on the carrier website, not the COI, and confirm the policy is active.
- For jobs over $10,000, ask to be named as additional insured for the project duration.
- Confirm the business name on the COI matches the name on your contract.
Five steps. Under an hour of your time. That work is the difference between a project that goes sideways and stays the contractor’s problem, and one that goes sideways and becomes yours. Check contractor insurance every time, on every job, before the first shovel hits the ground.
Skip the state databases
A Trade Check record shows the license, insurance, identity and standing we checked, and the date we checked it. Free to read, no account.
Check a contractor